
For years, the digital-money debate asked which instrument would win. September 2026 suggested a more practical answer: different forms of regulated digital money may coexist—provided they can interoperate.
On September 21, the Eurosystem launched Pontes, enabling wholesale tokenized-asset transactions to settle in central-bank money. On September 28, Swift reported that most of the first 17 banks using its blockchain ledger had conducted 24/7 real-time tokenized-value payments across six continents for institutional settlement, corporate treasury and interbank funding.
Three days after Pontes, Capgemini’s World Payments Report 2027 framed the commercial stakes. Its survey of 1,110 large corporations and 300 banking executives found substantial dissatisfaction with cross-border payments and estimated that stablecoins, tokenized deposits and CBDCs could account for approximately 4% of global payment volume by 2030.
Three instruments, three balance sheets
| Instrument | Issuer and liability | Principal advantage | Core challenge |
| CBDC | Central-bank liability | Risk-free settlement assets and possible public-policy reach | Privacy, adoption, disintermediation and operating-model design |
| Tokenized deposit | Commercial-bank deposit represented digitally | Preserves the deposit relationship and bank liquidity model | Interbank interoperability and settlement across separate ledgers |
| Regulated stablecoin/payment token | Private licensed issuer backed by reserves | Programmability, 24/7 availability and platform reach | Reserve quality, redemption, regulatory consistency and financial-crime controls |
These are not interchangeable products. Their issuer, legal claim, liquidity treatment and redemption architecture differ even when each uses a wallet or distributed ledger. The common infrastructure requirements are identity, compliance, programmability, interoperability and operational resilience.
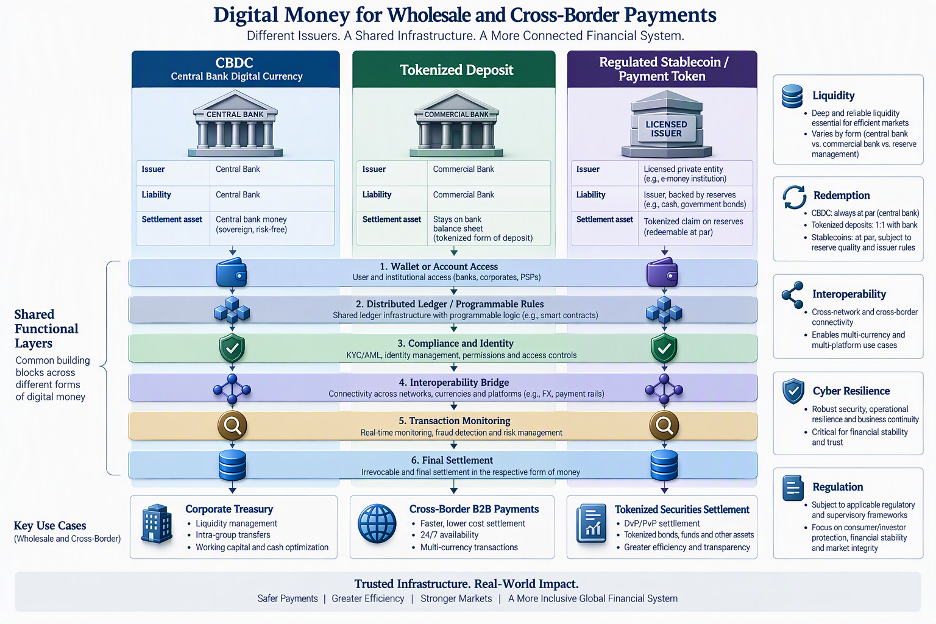
CBDCs, tokenized deposits and regulated stablecoins may use similar digital infrastructure, but they differ fundamentally in issuer, liability, liquidity model and regulatory treatment.
The commercial case is moving into treasury
Capgemini found that 74% of corporations surveyed described cross-border payments as slow, costly and unpredictable, while only one-third were satisfied with their primary banking partner. Although 71% would prefer a bank for tokenized payments at equivalent cost and quality, nearly 60% were open to stablecoin services from non-bank providers if banks failed to keep pace.
This creates both an opportunity and a defensive imperative for banks. Tokenized deposits can protect customer balances and enable programmable treasury services. Stablecoins can extend reach across digital platforms. CBDCs can provide settlement finality. But value emerges only when institutions solve real corporate problems: payment status, liquidity visibility, reconciliation, FX transparency and fraud prevention.
GCC/MEA: regulation is becoming a design input
The UAE offers a particularly relevant model. The CBUAE’s Digital Dirham framework adopts phased implementation, a two-tier intermediated model and wallet-based access. Its tested use cases include tokenized-asset settlement, programmable social payments, tourist wallets and sub-wallets.
Separately, the UAE Payment Token Services Regulation distinguishes issuance, conversion, custody and transfer activities. It requires licensing or registration, reserve protection, redemption controls, AML/CFT safeguards and customer-protection measures. Banks cannot directly act as payment-token issuers under the regulation but may establish a subsidiary or related entity subject to the applicable requirements.
For GCC banks, the strategic question is therefore not “blockchain or no blockchain.” It is which liability to issue or distribute, which use case justifies it, and how it will connect with existing core banking, treasury, compliance and payment systems.
The execution agenda
Institutions should prioritize:
- corporate treasury and cross-border settlement use cases with measurable friction;
- clear legal treatment of ownership, redemption and settlement finality;
- interoperability across conventional and tokenized rails;
- pre-transaction sanctions, AML and wallet-risk controls;
- liquidity and reserve management;
- cyber-resilient custody and key management; and
- reconciliation with the general ledger and regulatory reporting.
The September message was clear: tokenized money is becoming financial infrastructure, not simply a digital-asset product.
Infographic recommendations
- Three Forms of Digital Money: comparing issuer, liability, reserve, settlement, distribution and primary user.
- Corporate Cross-Border Payment: Today vs. Tokenized Model: highlight intermediaries, reconciliation points and compliance gates without claiming unsupported savings.
- GCC Digital-Money Architecture: central bank, licensed banks, token issuers, wallets, corporates and cross-border bridges.